If your income stopped, would your family manage?
Independent insurance advice built around your income and the people who depend on it.
Life, critical illness & income protection.
Advice on how much cover you need.
Advising clients nationwide.
 .
Protect the life you have built.
Your home, your family and the future you are building all depend, in some way, on your financial security. If you died, became seriously ill or were unable to work, the right protection could help hold things together and prevent a difficult time becoming a financial crisis.
The cover you need depends on your circumstances: your mortgage, your income, the people who rely on you and the commitments you would want to protect. Whether you are arranging cover for the first time or reviewing existing policies, good advice helps you work out what to put in place, how much cover is appropriate and how long it should run. If you are starting from the beginning, our guide to what protection insurance is and whether you need it explains how the main types work.
At AV Trinity, we advise on life insurance, critical illness cover and income protection from across the whole market, so what we recommend fits your circumstances rather than one insurer’s range. Based in Tunbridge Wells, we advise clients across Kent, East Sussex and the UK, in person, by telephone or by video.
What would you live on if you could not work?
If illness or injury stopped you working tomorrow, how long could your savings cover the mortgage, household bills and family costs?
You might receive enhanced sick pay from your employer, but that could reduce after a few months. Otherwise, you may have to rely on Statutory Sick Pay (SSP), which is considerably less than most people earn. And while your income falls, your outgoings do not. Our article on whether you could still pay your mortgage if something went wrong looks at what that gap means for a household.
What would SSP mean for you?
Statutory Sick Pay provides a limited safety net for eligible employees. At £123.25 a week, it represents a small proportion of a typical salary. The higher your earnings, the bigger the gap between what you normally earn and what you receive.
The self-employed receive nothing at all.
£10,000 a year
£123.25 of £192 a week, or 64%
£20,000 a year
£123.25 of £385 a week, or 32%
£40,000 a year
£123.25 of £769 a week, or 16%
£60,000 a year
£123.25 of £1,154 a week, or 11%
£120,000 a year
£123.25 of £2,308 a week, or 5%
£240,000 a year
£123.25 of £4,615 a week, or 3%
Figures are illustrative. SSP is taxable, and the amount received after deductions will differ. Eligibility and entitlement depend on the applicable rules.
What would happen to your family’s finances if you died?
If your income disappeared tomorrow, could your family still afford the mortgage, household bills and everyday living costs?
Savings might help for a while, but replacing an income can be difficult, particularly when your family is already dealing with a bereavement.
What help would the state provide?
Your spouse or civil partner might be eligible for Bereavement Support Payment. Depending on their circumstances, this consists of an initial payment followed by monthly payments for up to 18 months.
This support can help with immediate expenses, but it is not designed to replace a salary or cover your family’s long-term financial needs.
Bereavement Support Payment
If you have dependent children
£3,500 upfront
£350 a month for 18 months
Total: £9,800
If you do not have dependent children
£2,500 upfront
£100 a month for 18 months
Total: £4,300
Then the payments stop.
Illustrative totals based on the rates published by GOV.UK. Eligibility conditions apply.
When illness, injury or death changes your circumstances, the financial consequences can extend well beyond lost earnings. Your family may need financial security, you may face additional costs after a serious diagnosis, or you may need an income while you recover. Different types of protection address these risks.
Which type of cover do you actually need?
Often more than one.
The three work differently and protect against different things, so the useful question is not which one to pick, but what combination fits your circumstances and your budget.
Life insurance
Financial protection for the people you leave behind.
What it pays
A lump sum, or in some policies a regular income, if you die while covered.
Typically used for
Mortgage commitments and family financial security.

Critical illness cover
Financial support if you are diagnosed with a serious illness.
What it pays
A single, tax-free lump sum on diagnosis, to use however you need to.
Typically used for
Adapting to changed circumstances or covering additional costs.

Income protection
A replacement income if illness or injury stops you working.
What it pays
A regular income after a waiting period, for as long as you are unable to work.
Typically used for
Helping cover everyday living costs while you are unable to work.
The right cover depends on your income, your financial commitments, the people who depend on you and how long you need protection for. We can help you work out the right combination.
If you are protecting a business rather than a household, the cover works differently. Our business protection page explains how it works, including key person insurance and shareholder protection.
What protection insurance meant for one of our advisers.
In 2015 Louise Baughan, one of our advisers, was diagnosed with colon cancer. She and her husband had arranged a combined life insurance and critical illness policy years earlier, when they bought their home together.
Her claim was accepted in January 2016, two months after the diagnosis, and paid £256,000. She has written her own account of what happened and what the money made possible.
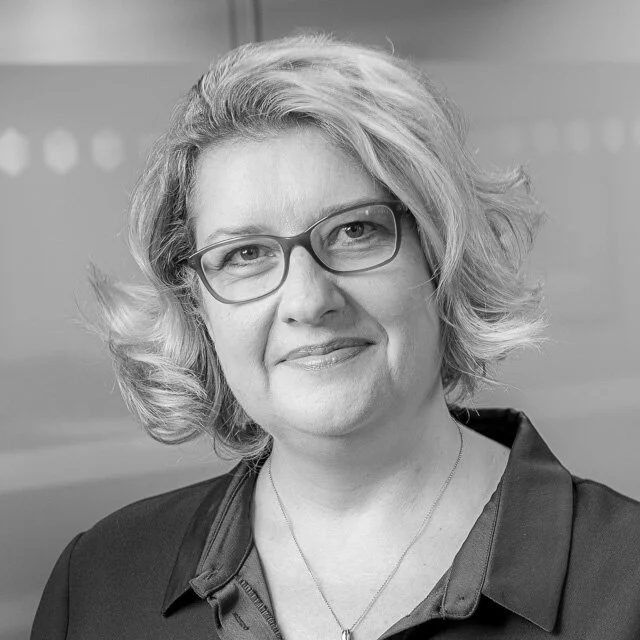
It’s easy to think “it will never happen to me…”. But as I know only too well, sometimes it does.
Louise Baughan FPFS
Chartered Financial Planner, AV Trinity
How do we work out the right cover for you?
We start with your life, not an insurance policy. We look at what needs protecting, what you already have in place and what you can comfortably afford, before recommending any cover at all.

What needs protecting?
We start with what your household spends and owes each month, and who relies on your income to meet it. That gives us the figure that would still need paying if you died, or if illness or injury stopped you earning.
What is already in place?
Cover you already hold counts towards that figure. A death in service benefit from an employer, company sick pay, or a policy taken out alongside a mortgage. We check what each one would pay, to whom, and for how long.
How much, and how long?
The difference between what your household would need and what you already have is the amount worth insuring. The term is a separate decision. Cover can run until the mortgage is repaid, until the children are independent, or until you reach retirement.
Which cover, and why?
Life cover, critical illness cover and income protection do different jobs, and are often held in combination. We advise across the whole market and compare the definitions and exclusions, not only the premiums, then review the cover as your circumstances change.
Whatever you already have in place, through an employer or alongside your mortgage, the question is whether it would be enough and would last long enough. We can tell you where you stand and help you close any gaps.
What our clients say about our protection advice.
As first-time buyers, my partner and I had very limited knowledge of the mortgage process and the various insurances required. Sean explained everything clearly and was always available for a call or email whenever we had questions.
Connor O'Brien
We reached out to AV Trinity as we wanted help understanding the difference in offers between various providers of life and illness insurance. Sean Adams was super helpful and really went above and beyond to ensure we found a package that met our needs at the best price available on the market. Very strongly recommend!
Dieter Declercq
Really helpful and great service for re-mortgage and life insurance. Super quick service with good advice. Would definitely recommend.
Laura Jones
Questions before you arrange a free initial consultation?
You may be wondering which type of cover you need, what it would cost, or whether what you already have would be enough.
These are the questions we are asked most often, so you can decide whether a free initial consultation is right for you.
About protection insurance
What is the difference between life insurance, critical illness cover and income protection?
They are all forms of protection insurance, but they pay out on different events. Life insurance pays if you die during the term. Critical illness cover pays a lump sum if you are diagnosed with one of the specific conditions listed in the policy. Income protection pays a regular income if illness or injury stops you from working, and keeps paying until you return to work, reach the end of the payment period, or the policy ends.
Do I still need cover if my employer provides it?
Often, yes. Employer cover is usually a multiple of salary paid on death, or sick pay for a set number of weeks, and both stop when you leave the job. It is worth establishing what yours would pay, to whom, and for how long before deciding whether anything further is needed.
Do I need protection if I have no children?
It depends on who would be affected financially. Life cover matters most where someone relies on your income, but critical illness cover and income protection protect you rather than only your dependants. Anyone with a mortgage, rent or regular commitments and no other means of meeting them has a reason to consider cover.
Choosing your cover
How much cover do I need?
There is no single formula. The usual starting point is what your household owes and spends, less anything already in place such as an employer scheme or an existing policy. The right figure also has to be affordable month after month, because cover that lapses protects nobody.
How long should the cover last?
Until the need ends. That might be when the mortgage is repaid, when the children become independent, or when you reach the age at which you plan to stop working. Different needs can justify different terms, which is one reason policies are often held in combination.
Is it better to have one policy or a combination?
That depends on what you are protecting against. The three types cover different events, so a household that would struggle if you died or if you could not work may need more than one. Where budget is limited, the order of priority depends on your circumstances.
Does it matter which insurer the cover is with?
Yes. Premiums vary between insurers, but so do the policy definitions, the conditions covered and the way claims are assessed. Two policies at a similar price can offer materially different cover, which is why we compare the terms rather than only the premium.
When should I review my protection?
Whenever your commitments or your income change. The type, the amount, the term and the person your cover pays are all fixed when the policy is taken out, and any of them can fall out of step with your life without anything going wrong.
The usual prompts to check are a new or larger mortgage, marriage or separation, a new baby, school fees or other long commitments, a new job or a lost employer scheme, becoming self-employed, a significant rise in income, and an existing policy nearing its end.
Should life cover be written in trust?
Often, yes. A policy written in trust pays out to the people you have named rather than into your estate, so the money can usually reach them without waiting for probate, and it generally falls outside your estate for inheritance tax.
It is not automatic and it is not always appropriate. Whether a trust suits your circumstances, and which type, is something to work through before the policy starts, because changing it afterwards is harder.
Cost and claims
What affects the cost of protection?
Mainly your age, your health, whether you smoke, the amount of cover and the length of the term. Your occupation and pastimes can also matter, particularly for income protection. Cover generally costs less the earlier it is arranged, because age and health are the two largest factors.
Can my premiums go up?
It depends on the type of policy. Guaranteed premiums stay the same for the whole term. Reviewable premiums are reassessed periodically and can rise. We will tell you which you are being quoted and what that is likely to mean over the life of the policy.
Do protection policies actually pay out?
Yes. However, claims are usually declined where information was not disclosed at application, or where the condition did not meet the policy definition, which is why an accurate application and the right definitions matter.
About your free consultation
What happens in a free initial consultation?
It is a conversation rather than a sales meeting. We will talk about your circumstances, what you already have in place and what you are trying to protect, then explain how we can help. It is free, there is no obligation to proceed, and we advise clients across the UK.
Can I just call instead?
Of course. Call us on 01892 612500, Monday to Friday, 9am to 5pm, and we will arrange it from there.
Arrange your free initial consultation.
AV Trinity provides whole-of-market advice on life insurance, critical illness cover and income protection, from Tunbridge Wells to clients across the UK.
Tell us what you are looking for and we will arrange a conversation with the right adviser. Whether you are arranging cover for the first time, reviewing policies you already hold, or working out what your employer benefits would actually pay, we can help.
Fill out the form and we will arrange your free initial consultation.
There is no pressure and no obligation to take advice. Your details are kept private and used only to respond to your enquiry.
Why choose AVT?
Chartered Financial Advice.
Fully independent.
Free initial consultation.
Whole-of-market protection.
Ongoing cover reviews.
Our location.
AV Trinity Limited
Oakhurst House
77 Mount Ephraim
Tunbridge Wells
Kent
TN4 8BS
Areas we cover.
We advise clients across the UK. Locally, we support clients throughout Kent, including Ashford, Maidstone, Sevenoaks and Tonbridge. In East Sussex, we advise clients in areas including Bexhill, Crowborough, Eastbourne, Hastings, Heathfield and Uckfield.
Keep in touch instead. Get one short, free email a month from our specialists, covering practical ideas and insights from pensions to property.
Join over 900 subscribers, and you can leave whenever you like.
About this page
This page is for individuals, couples and families considering life insurance, critical illness cover or income protection, or reviewing cover they already hold. It may be particularly relevant if you have a mortgage or other long-term commitments, children or a partner who relies on your income, benefits provided through an employer, or if you are self-employed and would have no sick pay to fall back on.
Useful sources: GOV.UK Statutory Sick Pay guidance and GOV.UK Bereavement Support Payment guidance.
This page provides general information only and should not be treated as personal financial, tax or legal advice. AV Trinity provides financial advice and works alongside legal professionals where specialist trust drafting or estate advice is required.
Reviewed by Helen Carey FPFS, Chartered Financial Planner and Compliance & Operations Director, AV Trinity.
Last reviewed: October 2026